How Mortgage Rates Change What You Can Buy in Naples
How Mortgage Rates Change What You Can Buy in Naples
by Magdevys “Maggie” Rodriguez November 14, 2026
The first question most buyers ask me is “what can I afford?” The honest answer depends on the rate as much as the price. Mortgage rates change your monthly payment, and the payment is what decides what you can buy in Naples. Start with a payment you are comfortable with, shop more than one lender early, and keep your financing protected in the contract. I will not predict where rates are going. Here is how I help Naples home buyers think about rates right now.
Where rates are, from the official source
Freddie Mac’s Primary Mortgage Market Survey (PMMS) reported that the 30-year fixed-rate mortgage averaged 7.18 percent as of November 5, 2026, down from 7.24 percent the week before. The 15-year fixed averaged 6.57 percent. The PMMS is a national average for conventional, conforming purchase loans with 20 percent down and excellent credit, and it updates every Thursday at noon Eastern. Your own rate can be higher or lower. You can check the latest number on Freddie Mac’s PMMS page.
Start with the payment, not the price
A lender looks at principal and interest, then adds property taxes, homeowners insurance, flood insurance if it applies, and any HOA or condo fees. In Naples, insurance and association fees can move the monthly number as much as the rate does. That is why I ask buyers for a monthly payment they are comfortable with first, and then we work back to a price range.
What a half point does
Here is simple math, not a forecast. On a $400,000, 30-year fixed loan, principal and interest at 7.18 percent is about $2,710 a month. At 6.68 percent it is about $2,576. That half point is roughly $134 a month, before taxes and insurance. Small rate differences add up, which is why shopping lenders matters.
Shop lenders early
Talk to more than one lender before you start touring, and ask each for a Loan Estimate on the same day so you are comparing the same market. The Consumer Financial Protection Bureau’s Loan Estimate guide shows what to compare: the rate, points, lender fees and cash to close. A strong pre-approval also makes your offer more believable to a Naples seller.
Protect the offer with contingencies
Keep a financing contingency in your contract unless you and your lender are sure you do not need it. Ask your lender how long a rate lock lasts, and match your closing date to it. If the payment only works at one exact rate, slow down and widen your price range before you write an offer.
For the bigger market picture, read my post on what buyers need to understand about the 2026 Naples market, or start your search on my buy page.
Featured home: 4109 29th Pl SW
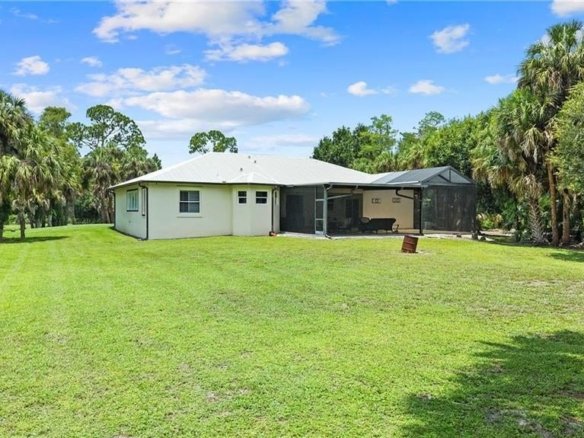
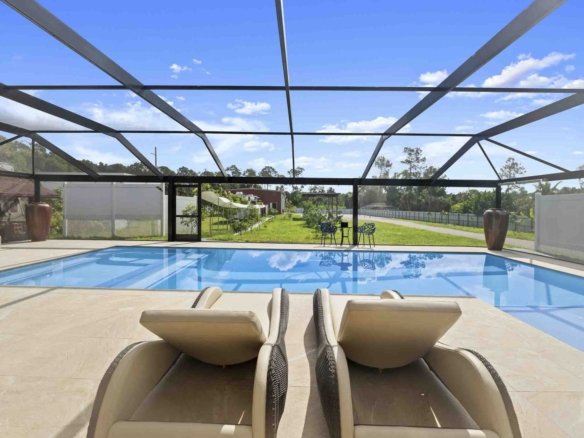
My listing at 4109 29th Pl SW in Golden Gate City shows how the payment conversation works on a real house. Offered at $699,000:
- 4 bedrooms and 3 full baths, with about 2,767 square feet of living area
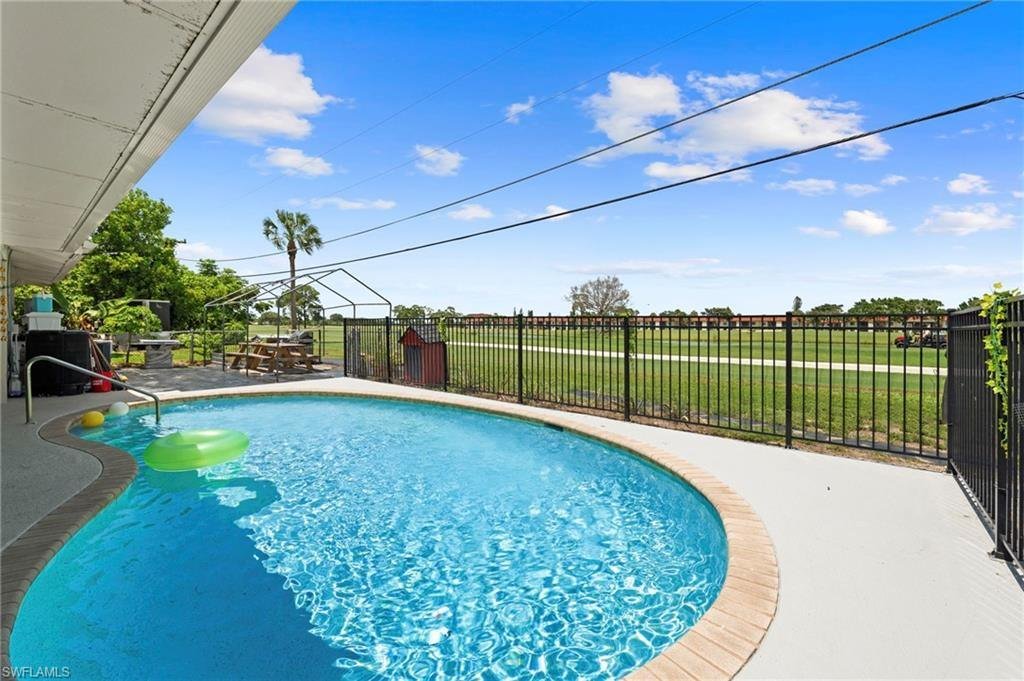
- A pool home on an oversized 0.34-acre lot that backs to The Gate Golf Club
- An updated kitchen with white cabinetry, quartz counters and a large island
- A separate side efficiency with its own private entrance
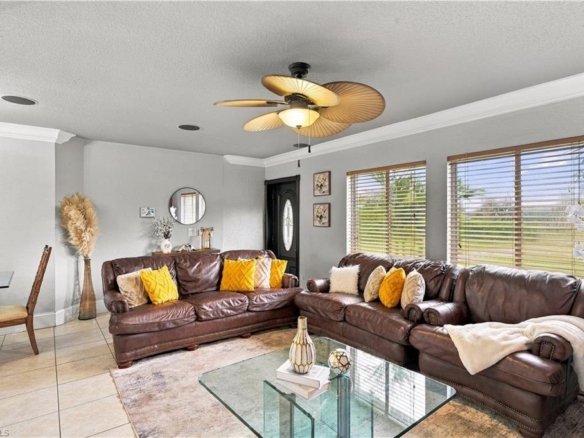
As an example only: with 20 percent down, the loan would be $559,200. At the November 5 PMMS average of 7.18 percent, principal and interest would be about $3,788 a month, before taxes and insurance. Your lender will give you your real numbers. See the photos and details on the 4109 29th Pl SW listing page. Ask me what conveys; do not assume furniture in the photos is included.
How I help
I help you set a comfortable payment, connect with lenders early, and write offers that keep your financing protected. I will not guess where rates are headed. In English and Spanish, since 2013.
How do mortgage rates affect what I can buy in Naples?
The rate changes your monthly principal and interest, and lenders qualify you on the total monthly payment. A higher rate means a lower price for the same payment, and a lower rate means the opposite.
What is the current average mortgage rate?
Freddie Mac’s PMMS reported a 30-year fixed average of 7.18 percent as of November 5, 2026. It updates every Thursday at noon Eastern, and your own rate depends on your credit, down payment and loan type.
Should I wait for rates to drop before buying?
I do not predict rates. If the payment works for you today and the home fits, waiting is a guess. If the payment only works at a lower rate, widen your price range or keep saving.
How many lenders should I talk to?
More than one. Ask each for a Loan Estimate on the same day so you can compare the rate, points and fees side by side.
Ready to run your numbers? Talk to a lender and to me. Contact me here, or call or text (239) 289-0749. Se habla español.
Your next step: search every home for sale in Naples, check the latest Naples market report, or if you are thinking of selling, find out what your home is worth and read my guide to selling in Naples.
Join The Discussion