How Much Down Payment Do Naples Buyers Usually Need?
How Much Down Payment Do Naples Buyers Usually Need?
by Magdevys “Maggie” Rodriguez November 19, 2026
A lot of buyers I meet think they need 20 percent down before they can even look. You usually don’t. The down payment for a Naples home purchase depends on your loan: some conventional loans allow as little as 3 percent for eligible buyers, FHA allows 3.5 percent with a 580 or higher credit score, and eligible veterans can often buy with no down payment on a VA loan. Putting 20 percent down on a conventional loan lets you skip mortgage insurance. The right number for you comes from a lender pre-approval, not from an average.
New to buying here? My guide to buying in Naples covers the whole process. This post is about the cash you bring to closing.
Down payment myths I hear every week
- “I need 20 percent.” Not for most loan types. Twenty percent is the point where a conventional loan no longer needs private mortgage insurance, not a minimum.
- “The down payment is all the cash I need.” It isn’t. You also need closing costs, your escrow deposit when the contract is signed, inspections, insurance and sometimes reserves. My post on the hidden costs of buying in Naples walks through them.
- “A gift from family doesn’t count.” It often does. Many loan programs accept documented gifts, and some accept grants and down payment assistance.
The main loan types and their minimums
- Conventional (Fannie Mae): Fannie Mae’s 97 percent loan-to-value options allow 3 percent down on a one-unit primary home. The standard version needs at least one first-time homebuyer, and HomeReady has income limits instead. Gifts, grants and down payment assistance can be used.
- Private mortgage insurance: the Consumer Financial Protection Bureau explains that conventional loans with less than 20 percent down usually require PMI, which protects the lender and adds to your payment. At 20 percent down, PMI isn’t required.
- FHA: HUD’s rules allow maximum financing, which is 3.5 percent down, with a credit score of 580 or higher. Scores from 500 to 579 are limited to 90 percent financing, so 10 percent down. FHA loans are for a primary home and come with their own mortgage insurance.
- VA: VA-backed purchase loans often need no down payment as long as the price isn’t higher than the appraised value, and they don’t carry PMI.
- Second homes, investment properties and larger loans: expect your lender to ask for more down. Ask early, especially if you are buying a seasonal home.
Florida Housing Finance Corporation also lists homebuyer loan programs offered through participating lenders. Rules and funding change, so ask your lender what is open when you apply.
The cash advantage
If you can pay cash, you don’t need a loan approval, so there is no financing contingency and no lender appraisal holding up the closing. Sellers often like that, and it can help in a multiple-offer situation. You should still do inspections and get insurance quotes. Some buyers pay cash and finance later, but talk to your lender and your tax advisor before you plan on that.
Get pre-approved first
Before we tour, I ask every financed buyer to talk to a lender. A pre-approval looks at your credit, income, debts and assets and tells you:
- Which loan types you qualify for
- Your minimum down payment for each one
- Your estimated monthly payment, including taxes, insurance and any mortgage insurance
- About how much cash you need at closing, not just for the down payment
Then compare a few down payment levels. Here is the simple math on a $775,000 price: 5 percent is $38,750, 10 percent is $77,500 and 20 percent is $155,000. Your lender tells you which of those your loan allows at that price, and what each does to your payment.
One more thing to plan for: under the new written buyer agreements, your agent’s compensation is set in your agreement with them. Sometimes the seller pays part or all of it, and sometimes it’s part of your cash to close. I go over that with you up front, so it’s in your budget.
Featured home: 2610 4th St NW
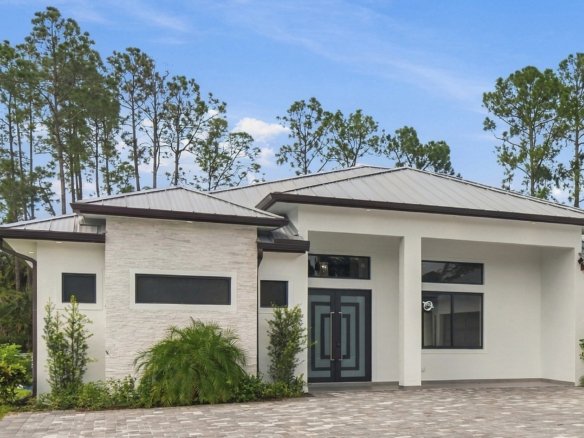
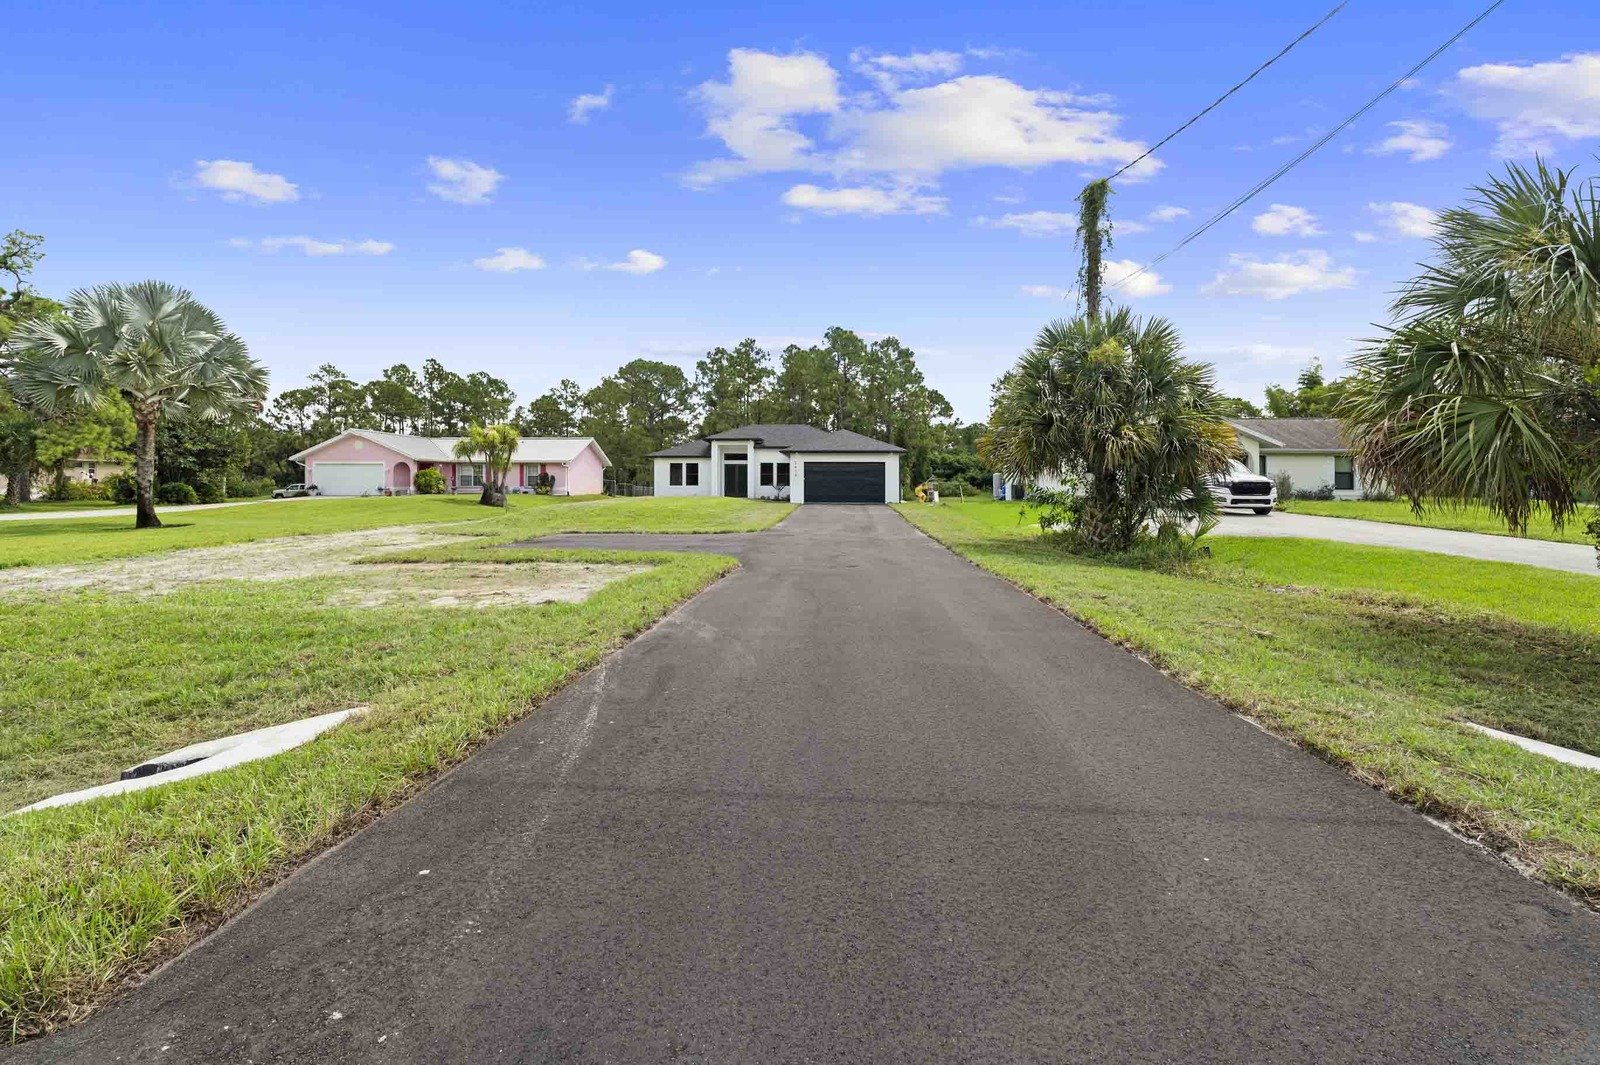
One of my listings in Golden Gate Estates, 2610 4th St NW, is brand new 2026 construction offered at $775,000 with no HOA:
- Three bedrooms, three full baths and a separate den on 1.14 acres
- A great room with 10 foot volume ceilings and an island kitchen with a walk-in pantry
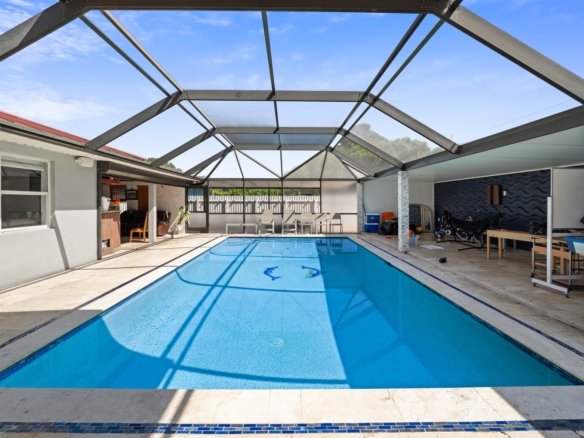
- A below-ground pool with a paver deck off the covered lanai
- 8 inch concrete block, impact windows and doors, a private well and a new septic system, all permitted and inspected in 2026
With a private well and septic, ask your lender early if they will want a water test or septic inspection. See the photos on the 2610 4th St NW listing page, or call me for a private showing.
How I help
I connect you with lenders who know Naples, help you compare loan options next to real listings, and keep your offer strong whether you put 3 percent down or pay cash. In English and Spanish, since 2013.
Do I need 20 percent down to buy a home in Naples?
No. Many buyers put down less. Some conventional loans allow 3 percent for eligible buyers, FHA allows 3.5 percent with a 580 or higher credit score, and VA loans often need no down payment. With less than 20 percent down on a conventional loan, you usually pay private mortgage insurance.
What is the minimum down payment for an FHA loan?
Under HUD’s rules, 3.5 percent with a credit score of 580 or higher. Borrowers with scores from 500 to 579 are limited to 90 percent financing, which means 10 percent down.
Can a gift be used for my down payment?
Often, yes. Many loan programs, including Fannie Mae’s 97 percent options, allow documented gifts, grants and down payment assistance. Your lender will tell you what paperwork is needed.
Is the down payment the only cash I need to buy?
No. Plan for closing costs, your escrow deposit at contract, inspections, insurance and sometimes reserves. Your lender’s Loan Estimate shows your estimated cash to close.
Ready to start? Read my Naples buyer guide, send me a message, or call or text me at (239) 289-0749 to set up a buyer consultation. Se habla español.
Your next step: search every home for sale in Naples, check the latest Naples market report, or if you are thinking of selling, find out what your home is worth and read my guide to selling in Naples.